
KRA Explains New Rental Tax Rules Targeting Landlords Living Abroad
By KASS MTV USA Newsroom | Nairobi, Kenya
Kenyans living abroad who earn rental income from property in Kenya are being urged to review their tax obligations following changes introduced under the Finance Act 2026.
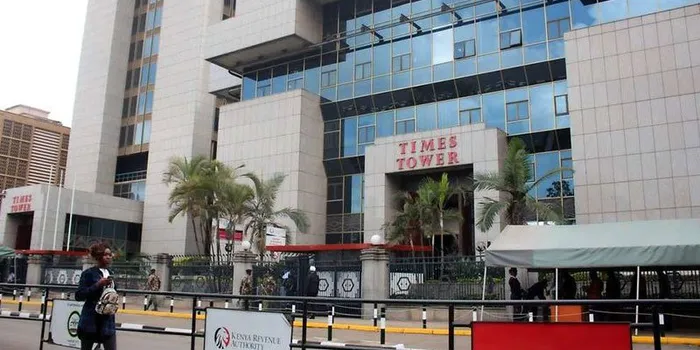
The Kenya Revenue Authority (KRA) says non-resident property owners earning rental income from Kenyan property are subject to a simplified tax framework that took effect from July 1, 2026.
Under the framework, rental income paid to a non-resident landlord is subject to 30 per cent tax on the gross rental income, with the tax treated as final. KRA’s current guidance lists residential rent at 30 per cent for non-residents, compared with 7.5 per cent under the Monthly Rental Income regime for qualifying resident landlords.
How the New Tax Works
For example, a Kenyan living abroad who receives KSh100,000 in monthly rent from property in Kenya would have KSh30,000 deducted as tax, leaving KSh70,000 after the tax deduction.
Unlike arrangements where expenses can affect taxable income, the non-resident rental withholding is calculated on the gross rent.
KRA says non-residents earning rental income from Kenyan property must register under the applicable framework and file and pay the tax by the 20th day of the month following the month in which the income was earned, unless a resident agent is withholding the tax on their behalf.
Property Managers and Agents May Have Tax Responsibilities
The changes also affect people managing rental properties on behalf of non-resident owners.
Relatives, property managers, agents or other persons receiving rent on behalf of a non-resident landlord may have tax withholding and remittance obligations where the law requires them to act as an agent.
KRA has previously stated that rent paid to a non-resident is subject to 30 per cent withholding tax and that the tax is final for the non-resident landlord.
What About Landlords Living in Kenya?
The 30 per cent rate should not be confused with the Monthly Rental Income (MRI) regime applicable to qualifying resident landlords.
KRA’s current guidance states that the MRI rate is 7.5 per cent of gross residential rent for qualifying resident persons, with no deduction of expenses, losses or capital allowances from the gross rent.
The law therefore distinguishes between resident and non-resident landlords when determining how rental income is taxed.
Deadline for Payment
Non-resident landlords and those handling rental income on their behalf should pay particular attention to the monthly deadline.
KRA says the tax should generally be filed and paid by the 20th day of the following month, unless a resident agent is responsible for withholding and remitting the tax.
KRA’s guidance for Kenyans living abroad also states that income accrued or derived in Kenya remains subject to Kenyan tax obligations, even where the taxpayer is living outside the country.
What Landlords Living Abroad Should Do
Kenyans in the diaspora who own rental property in Kenya should:
- Confirm that their rental income and property details are properly registered with KRA.
- Establish whether they are classified as resident or non-resident for tax purposes.
- Review agreements with property managers, agents or relatives collecting rent on their behalf.
- Ensure the applicable tax is withheld and remitted on time.
- Keep records of rental income and tax payments.
KRA says the Finance Act 2026 introduced a simplified framework specifically covering non-residents earning rental income from Kenyan property and has advised affected taxpayers to review their rental arrangements and compliance requirements.
The changes come as Kenya continues to strengthen the administration and collection of taxes on income generated from property, including income earned by Kenyans who live outside the country but maintain investments in Kenya.
